How to Read Vehicle Value and Claim Payments in a Comprehensive Auto Policy
Published: October 14, 2026 • Reading Time: 7 min • Last Updated: October 14, 2026
Learn what a vehicle value in a comprehensive auto policy means, how a claim is assessed, and how to review coverage, deductibles, valuation terms, and supporting documents.
Contents
- What does vehicle value in a policy mean?
- Why accurate vehicle details matter
- How is a claim payment assessed?
- Why might a payment differ from the vehicle value?
- Policy sections to review together
- How to follow a claim file
- Comparing valuation records
- Practical preparation before a claim
- Conclusion: read value, coverage, and calculation together
- Frequently Asked Questions
This guide explains what a vehicle value in a comprehensive auto policy represents, how a claim payment is assessed, and which policy sections should be read together. The figure shown for the vehicle does not by itself tell you what will be paid after every loss. Coverage, the type of damage, any deductible, the repair assessment, and the policy wording all matter.
What does vehicle value in a policy mean?
A vehicle value field describes the basis on which the vehicle’s value is considered under the insurance contract. It may relate to details such as make, model, model year, trim, equipment, mileage, condition, and the valuation approach used when the policy was issued. The value recorded at that time and market conditions on the date of a later claim are not automatically identical. Read the policy definition and related conditions together to understand which date and method apply.
Asking prices, completed sale prices, and an insurer’s valuation are different concepts. Advertised listings reflect what sellers ask; they do not alone establish a completed transaction or determine the amount used in a claim calculation. Likewise, the presence of a vehicle value in the policy does not mean that the same amount is payable for every kind of damage.
Why accurate vehicle details matter
For a valuation to reflect the insured vehicle, the description in the policy should match the vehicle itself. An incorrect or incomplete model year, trim, fuel type, or equipment description can affect how the vehicle is identified and assessed. Compare the policy details with the registration documents. If accessories or equipment were added later, check how the policy treats them and whether they fall within the stated coverage.
How is a claim payment assessed?
After a claim is reported, the first step is to assess whether the event and resulting damage fall within the policy’s coverage. The review may consider exclusions, deductibles, and any special conditions. The next steps establish whether the vehicle can be repaired, what repairs are needed, and how the related costs are assessed. The payment or repair process depends on those findings and on the method described in the policy.
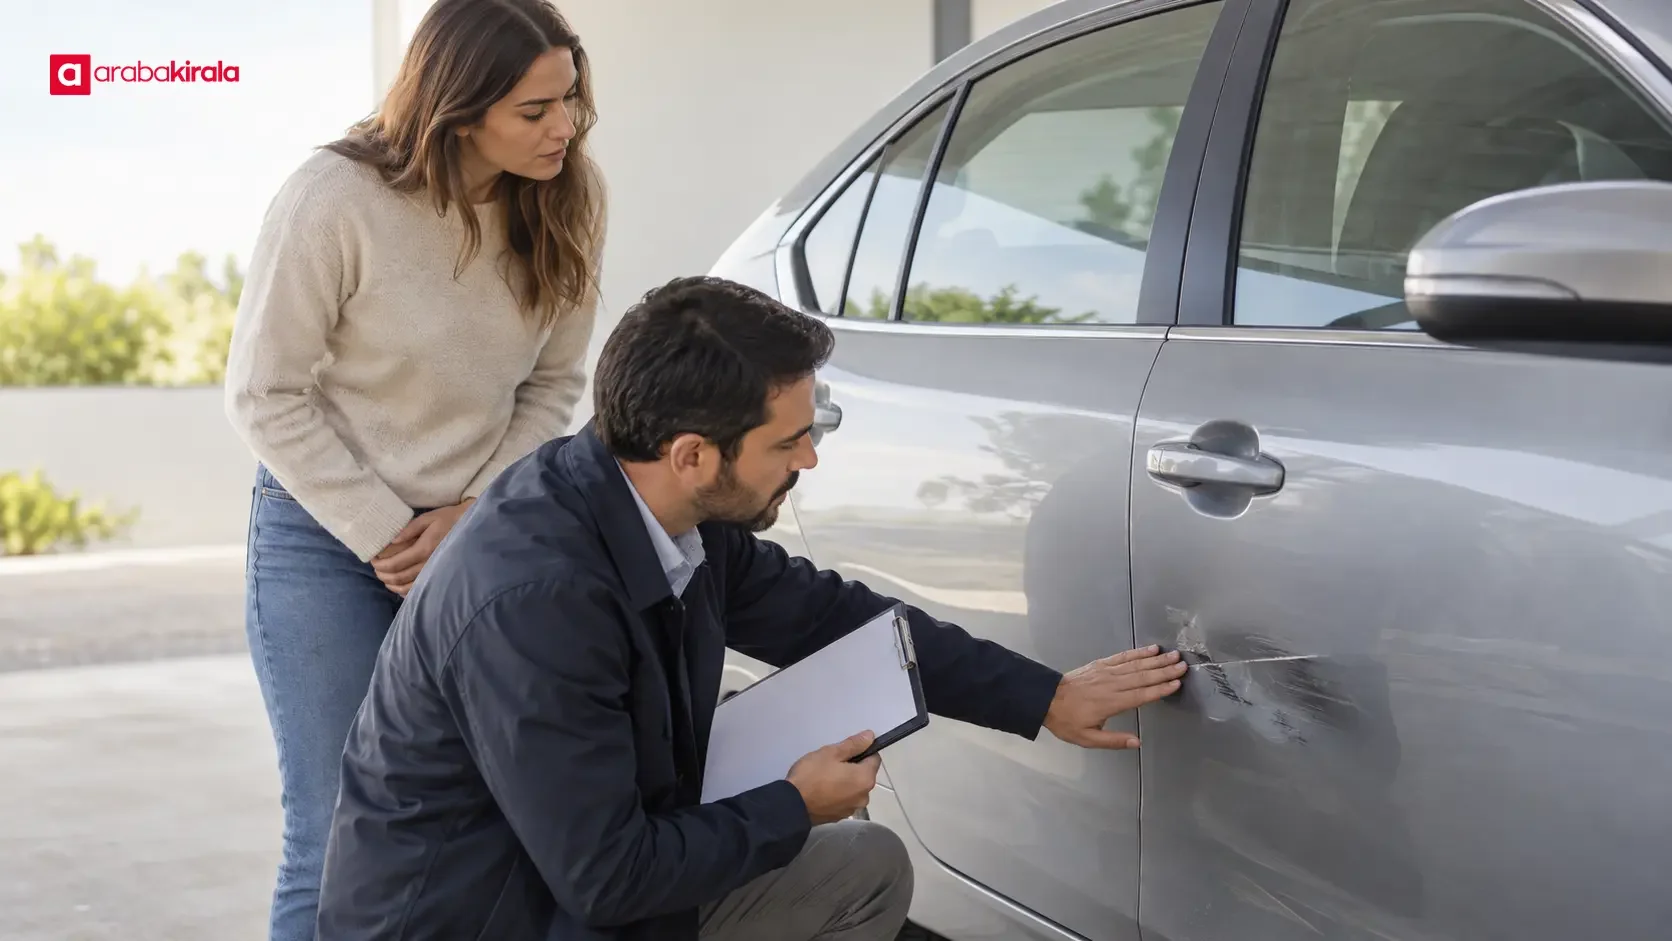
For partial damage, the assessment generally concerns the affected parts and the work required to repair them. Review how parts, labour, applicable taxes, and the proposed repair method appear in the claim explanation. If the policy has a deductible, check which amount or percentage applies and where it enters the calculation. A deductible may leave a defined portion of a covered loss with the policyholder; the precise application depends on the contract wording.
When damage is severe or repair is not considered economical, the method can differ from a partial repair assessment. Read the policy’s definition of a total loss, the valuation date, how the vehicle’s pre-loss condition is considered, and whether salvage or residual value affects the calculation. Do not assume these terms are handled identically in every policy; confirm their meaning in your own documents.
Why might a payment differ from the vehicle value?
A vehicle value in a policy does not make an event outside the coverage payable. The claim outcome can depend on the covered loss, the proven damage, any deductible, the policy’s valuation basis, and the repair or total-loss method used in the file. Only part of a loss may be covered. Treat the vehicle value as one element of the contract, then read it alongside the coverage and payment provisions.
Policy sections to review together
- Vehicle description: Do the make, model, model year, trim, and equipment details match the insured vehicle?
- Valuation basis: Which date or method is used to establish value? Does the policy state a fixed amount or refer to another valuation approach?
- Coverage and exclusions: Which coverage applies to the type of damage, and what circumstances are excluded?
- Deductible: Which claims does it apply to, and at what stage of the calculation is it taken into account?
- Repair assessment: How are parts, labour, and the type of replacement parts determined?
- Total-loss terms: What criteria, valuation date, and treatment of salvage or residual value are described?
- Payment and documentation: Which documents are required for the file, and what records explain the calculation?
If a policy phrase is unclear, note the clause number and request an explanation. Try to identify where that explanation appears in the policy or the written claim assessment rather than relying only on a verbal summary. For a policy tied to a particular vehicle, checking the wording against the vehicle documents can help resolve errors early.
How to follow a claim file
After damage occurs, record the date, location, and circumstances as accurately as possible. Keep photographs, repair assessments, expert reports, and other requested documents together. Document requests can vary with the type of loss and what the file reviewer needs to establish, so obtain the current list for your claim from the team handling it.
When you receive a payment calculation, review the individual entries as well as the total. Does it show the accepted repair cost, items treated as outside coverage, the deductible, and any other adjustment separately? If the calculation does not appear to match a report, ask which document or policy clause supports the disputed entry. Follow the review or appeal route described in your policy and claim communications.
Comparing valuation records
Check that the vehicle details used in a valuation match the registration documents and the actual equipment. If mileage, prior damage, or condition was included, ask which records support those inputs. When comparing valuation documents prepared on different dates, account for the date difference: market conditions and the vehicle’s condition can change over time.
Practical preparation before a claim
Keep a copy of the policy, the vehicle details, and claim contact instructions somewhere accessible. Reviewing the coverage table, deductible clauses, and initial reporting requirements helps you understand what information may be needed if damage occurs. This preparation cannot guarantee a payment outcome, but it can make the file easier to follow and the supporting information clearer.
Before renewal or a new policy, report changes to vehicle details and ask how added equipment is treated. Keep in mind that vehicle value, a coverage limit, and the claim calculation are separate concepts. When your question concerns a particular policy clause or claim file, request a written explanation based on that document.
Conclusion: read value, coverage, and calculation together
To understand vehicle value in a comprehensive auto policy, check the vehicle description and valuation method. To understand a claim payment, read coverage, exclusions, deductibles, and the repair or total-loss terms together. Then follow the documents and calculation behind each claim entry. As a next step, mark these sections in your own policy and ask the issuing office for a written explanation of any unclear clause.
Frequently Asked Questions
Is the vehicle value in the policy the amount payable after a claim?
No single figure answers that question on its own. The outcome depends on whether the event is covered, the type of damage, the policy’s valuation basis, any deductible, and the claim calculation. Read the vehicle value provision with the payment terms.
Is a partial-damage payment based on the vehicle’s full value?
A partial-damage assessment generally focuses on repairing the affected areas and the related costs. Coverage and any deductible may also affect the result. Review how the claim file determined the parts and labour entries.
Which documents matter in a total-loss calculation?
The policy terms, documents confirming the vehicle description, a damage assessment, and the records used in the valuation may all be relevant. Ask the team handling the file for the document list specific to your claim and how each item feeds into the calculation.
Is a deductible subtracted from the vehicle value?
The policy determines which amount or percentage the deductible applies to and where it enters the calculation. Do not assume every policy uses the same method. Compare the deductible clause with the deduction shown in the claim assessment.
What should I do if the policy lists incorrect vehicle details?
Contact the office that issued the policy promptly and request a written correction. Provide documents that show the current vehicle details, then ask for written confirmation of how the correction affects the valuation and coverage.
Legal Disclaimer: All content, articles and information on the Araba Kirala website are provided solely to inform users. No information shared on this website constitutes definitive advice or guidance. Araba Kirala Teknoloji A.Ş. and its authors cannot be held responsible for any direct or indirect damages arising from the application of information on the website. For all questions and requests regarding car rental, please contact the office from which you will rent your vehicle.