What Does Optional Motor Third-Party Liability Cover?
Published: October 16, 2026 • Reading Time: 7 min • Last Updated: October 16, 2026
Learn how optional motor third-party liability relates to compulsory traffic insurance, which third-party claims it may address, and what coverage terms and limits to check.
Contents
- What is optional motor liability coverage?
- Which types of claims may it address?
- Property damage and bodily injury
- Claims for non-economic loss
- How is it different from compulsory traffic insurance?
- Does İMM cover damage to the rented car?
- What should you check when renting a vehicle?
- How to read policy limits and wording
- In short: clarify the scope before you decide
- Frequently Asked Questions
Optional motor third-party liability coverage is designed to address certain legal liability claims arising from the use of a motor vehicle, within the scope and limits written in the policy. It may provide an additional layer for covered claims that exceed compulsory traffic insurance limits. This guide explains the types of third-party losses that may be involved, how the cover differs from compulsory insurance, and what to read in rental or insurance documents.
What is optional motor liability coverage?
Optional motor liability, commonly referred to as İMM in Turkey, concerns legal liability connected with the use of a vehicle and losses suffered by third parties. “Optional” distinguishes it from compulsory traffic insurance. Its practical purpose is to provide additional cover for a qualifying liability claim beyond the applicable compulsory insurance limit, up to the amount and within the conditions stated in the relevant policy.
The word “cover” should not be read as an automatic promise to pay every loss after every accident. Whether the insured is legally responsible, whether the claim falls within the policy wording, and which limits apply all matter. It is more useful to think of İMM as a defined layer of liability protection than as an all-purpose accident package.
Which types of claims may it address?
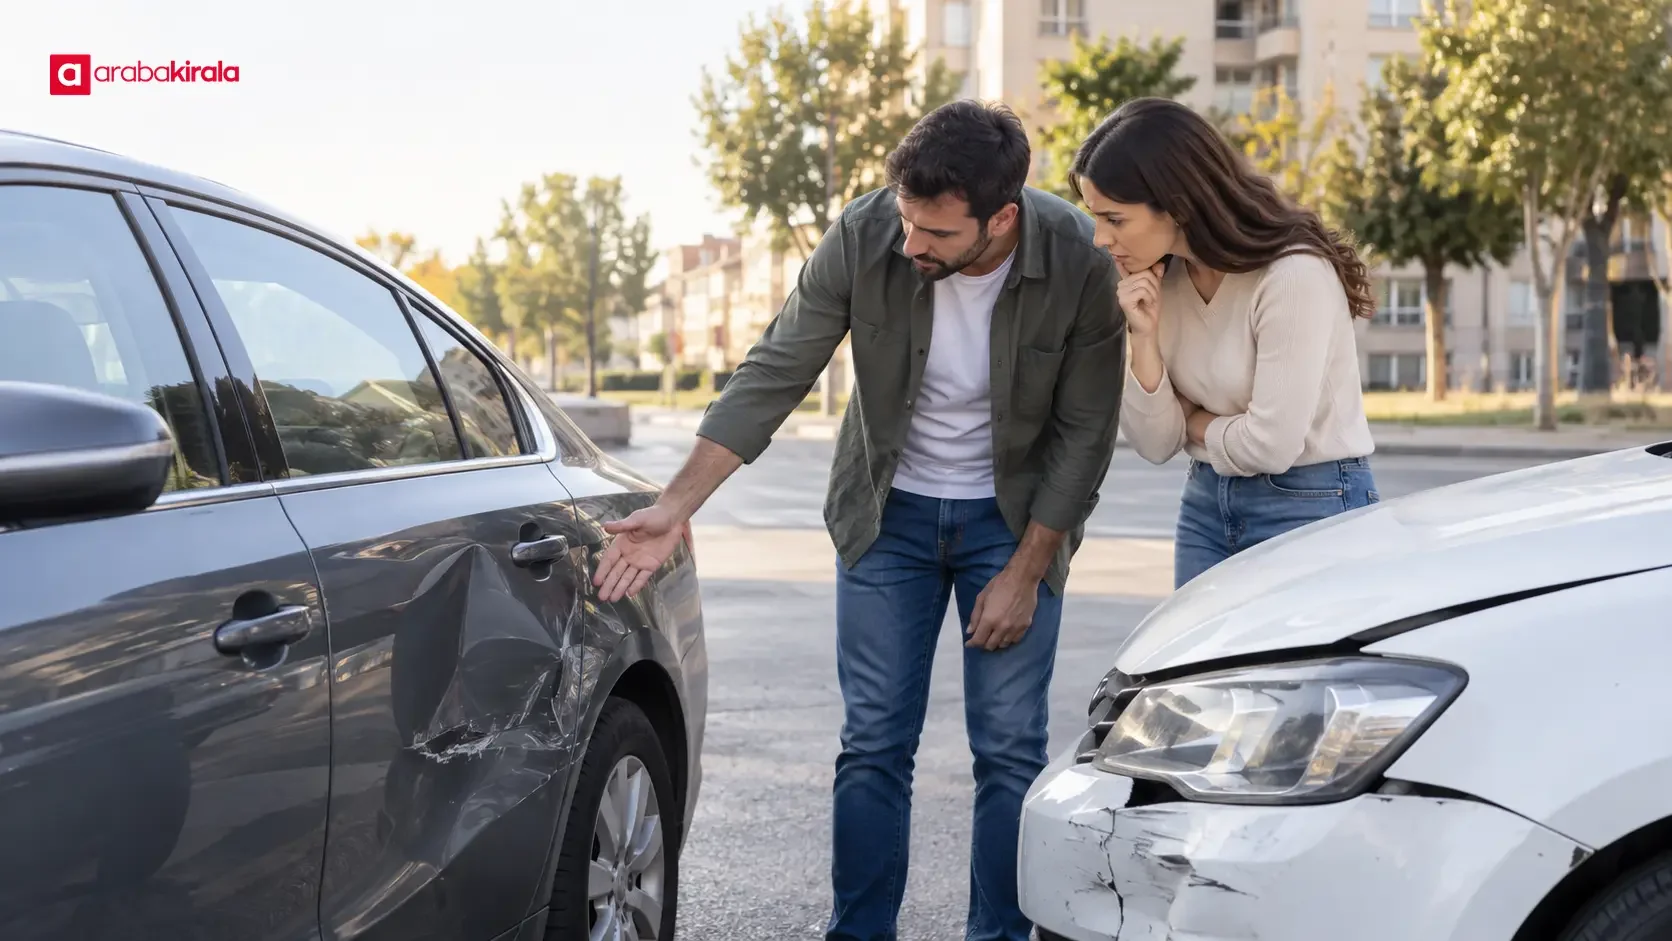
The focus is on liability claims relating to harm suffered by other people. Depending on the facts and policy wording, this may involve damage to another person’s vehicle or property, or claims associated with injury or death. Damage to another vehicle is a property loss; injury and death claims are bodily injury matters. Each claim is assessed in light of responsibility, the loss, and the applicable coverage.
The distinction between third-party liability and damage to the vehicle being driven is essential. Do not assume that İMM covers damage to the rented vehicle itself, the driver’s personal belongings, or the driver’s own medical costs. Those subjects may be dealt with under other forms of insurance or contractual arrangements. The document needs to identify the specific protection before you treat one cover as a substitute for another.
Property damage and bodily injury
Property damage concerns physical loss to someone else’s vehicle or other property. Bodily injury concerns claims related to a person being injured or killed. A policy may set separate limits for these categories or structure its limits differently. Looking only at a single headline amount can hide lower sublimits that apply to a particular type of loss. Check how the document uses phrases such as “per person,” “per accident,” or “property damage.”
Claims for non-economic loss
Claims for non-economic or moral damages require a separate check. The official İMM General Conditions state that such claims may be included through an additional agreement. Seeing İMM on a document therefore does not by itself establish that moral damages are covered. Look for a clear policy or endorsement provision and review any stated limit and conditions.
How is it different from compulsory traffic insurance?
Compulsory traffic insurance addresses defined third-party liability arising from the operation of a motor vehicle, under the applicable rules, general conditions, and limits in force for the incident. İMM can add protection for liability claims that are within its policy scope and exceed those compulsory limits. In simple terms, compulsory insurance is the required basic layer, while İMM is an additional layer with its own written scope and limits.
This relationship is not an unlimited payment guarantee. The nature of the claim and responsibility are assessed first, and then the relevant compulsory cover and İMM wording are applied. An İMM limit does not erase exclusions or automatically cover the full amount of any loss. The upper limit, covered claim types, and policy conditions define the potential protection.
Does İMM cover damage to the rented car?
The central purpose of İMM is the insured’s financial liability to third parties. It is not the same as cover for damage to the car being driven, such as a rented vehicle. Likewise, third-party liability cover does not mean that every type of damage to a rental vehicle will be waived or paid by an insurer. Read the vehicle damage provisions separately from the liability provisions.
This distinction is useful before a rental begins. Asking “Is there insurance?” does not tell you what the insurance covers. Check which vehicle and person the document relates to, which types of loss are included, and how excesses, limits, and exclusions are described. Similar sounding coverage names can serve different purposes in an insurance policy and a rental agreement.
What should you check when renting a vehicle?
Read the coverage language in the reservation and handover documents. Check whether İMM is expressly listed, what liability it concerns, and which categories of loss it addresses. If a phrase is unclear, ask the branch where you will rent the vehicle to explain the written terms. Do not apply conditions from a different vehicle, policy, or booking to your own rental.
- Look for an explicit reference to İMM among the listed covers.
- Confirm which person’s or vehicle’s liability the cover relates to.
- Check whether property damage and bodily injury limits are shown separately.
- Verify separately whether moral damages are included.
- Read the written explanations of excesses, exclusions, and notification or documentation requirements.
- Review protection for damage to the rental vehicle separately from İMM.
This review can help you understand the stated coverage before a loss occurs, but insurance does not replace safe driving. Follow traffic rules, operate the car carefully, and prioritize safety after an incident before following the relevant reporting steps. The records or documents required can depend on the applicable insurance and rental documents; if you are unsure, contact the branch that handed over the vehicle.
How to read policy limits and wording
A limit is the stated maximum amount for a particular coverage. Phrases such as “per person” and “per accident” indicate the basis on which a limit applies. A large total figure does not necessarily mean that every type of claim is covered up to that amount under the same conditions. Consider sublimits, additional agreements, and general conditions together.
The policy may also specify the territory where cover applies, the vehicle whose use is insured, and situations excluded from cover. Review the written policy or coverage certificate rather than relying only on a short verbal summary. If a term is difficult to interpret, point to the wording and ask the insurance or rental representative to explain what it means for that particular cover.
In short: clarify the scope before you decide
Optional motor liability coverage may provide an additional layer for covered third-party liability claims above compulsory traffic insurance limits, subject to the policy’s scope and limits. It is not the same as cover for damage to the car you are driving, and moral damages need separate confirmation. As a next step, read the coverage name, loss categories, limits, and exclusions in the rental documents. Ask the rental branch only about details specific to your vehicle and reservation that the written documents do not clarify.
Frequently Asked Questions
Does İMM replace compulsory traffic insurance?
No. İMM is separate from compulsory traffic insurance. It may add protection for qualifying liability claims above compulsory limits, subject to its own scope and policy limits.
Can İMM cover damage to the other driver’s car?
Damage to another person’s vehicle may be assessed as a property damage claim when the liability and policy conditions are met. Responsibility, the actual loss, policy scope, and limits affect the outcome.
Will İMM pay for damage to my rental car?
İMM concerns liability to third parties and is not the same as cover for damage to the rental vehicle. Review the rental documents’ vehicle damage provisions separately.
Are moral damages automatically included?
They should not be assumed to be included in every policy. The general conditions provide that moral damage claims may be included by additional agreement, so check for an explicit policy or endorsement provision.
What does the İMM limit mean?
It is the stated upper amount for covered claims. Check whether the limit applies per person or per accident and whether separate sublimits apply to different loss categories.
How can I find out whether a rental includes İMM?
Review the coverage section of the reservation and handover documents. If the presence, scope, or limits of İMM are unclear, ask the branch where you will rent the car to explain the written terms for that booking.
Legal Disclaimer: All content, articles and information on the Araba Kirala website are provided solely to inform users. No information shared on this website constitutes definitive advice or guidance. Araba Kirala Teknoloji A.Ş. and its authors cannot be held responsible for any direct or indirect damages arising from the application of information on the website. For all questions and requests regarding car rental, please contact the office from which you will rent your vehicle.