How to Read Notification Duties in a Vehicle Insurance Policy
Published: October 5, 2026 • Reading Time: 6 min • Last Updated: October 5, 2026
Learn how to find notification clauses, distinguish a notice from a claim, and organize records after an incident. Check policy-specific deadlines, channels, and document requests carefully.
Contents
- What does a notification duty mean?
- Where to find the relevant policy information
- Questions to answer while reading
- How to interpret time limits and contact methods
- Collecting information safely after an incident
- A practical first-record routine
- Reduce the risk of incomplete or inaccurate information
- Notification and claim assessment are different stages
- Frequently asked questions
- What if I cannot find a clear notification deadline?
- Is a phone call enough?
- Are photographs enough to submit a damage claim?
- How long should I keep the records?
- Next step: make a short process note from your policy
A vehicle insurance notification duty explains how an event must be reported to the insurer and what information may be needed. This guide shows you where to look in a policy, how an initial notice differs from a claim assessment, and how to keep useful records after damage or a collision. Deadlines, contact methods, and requested documents depend on the policy and the event, so use your own policy wording as the reference.
What does a notification duty mean?
Notification is the act of informing an insurer about an event that may affect the insurance relationship. Vehicle damage, a road collision, an attempted theft, or another event described in the policy may trigger a notice. Do not assume a universal list applies to every policy. Read the relevant coverage and duties together, because different coverages may call for different information or supporting documents.
A notice does not mean that a claim has been accepted or that a payment will be made. It records the event and initial details. A claim assessment may then consider what happened, whether the policy coverage applies, and which documents are needed. Keeping these stages distinct helps you avoid treating an acknowledgement of receipt as a final decision.
Where to find the relevant policy information
Do not read a policy as if it were only a list of coverage names. Special conditions, references to general conditions, notification methods, and document requirements may appear in separate sections. Use the contents page or search function, if available, to look for terms such as “notice,” “notification,” “claim,” “documents,” and “deadline.” Record the clause alongside the policy number and relevant coverage.
Questions to answer while reading
- Which events or changes must be reported?
- Is a reporting period stated, and how does the wording define its starting point?
- Which method is specified: phone, online form, email, or another channel?
- What initial details are requested, and what documents may follow?
- How can you obtain a reference number or written acknowledgement?
If a clause is unclear, do not draw a conclusion from its heading alone. Read its definitions, exceptions, and references to other sections. A policy may use terms in a specific sense that differs from everyday conversation.
How to interpret time limits and contact methods
If a policy states a time period, identify exactly what starts the clock. The wording may refer to when an event occurred, when it was discovered, or another defined starting point. Do not treat these as interchangeable. If the policy distinguishes calendar days from business days, preserve its exact language and ask how the calculation applies if needed.
The difference between sending a notice and having it received or completed can matter. Submitting a form alone may not show that the process finished or that attachments were included. Keep a reference number, automated receipt, or written confirmation. For a phone call, record the date, time, department contacted, and instructions received. A short written follow-up can help preserve a clear record.
Collecting information safely after an incident
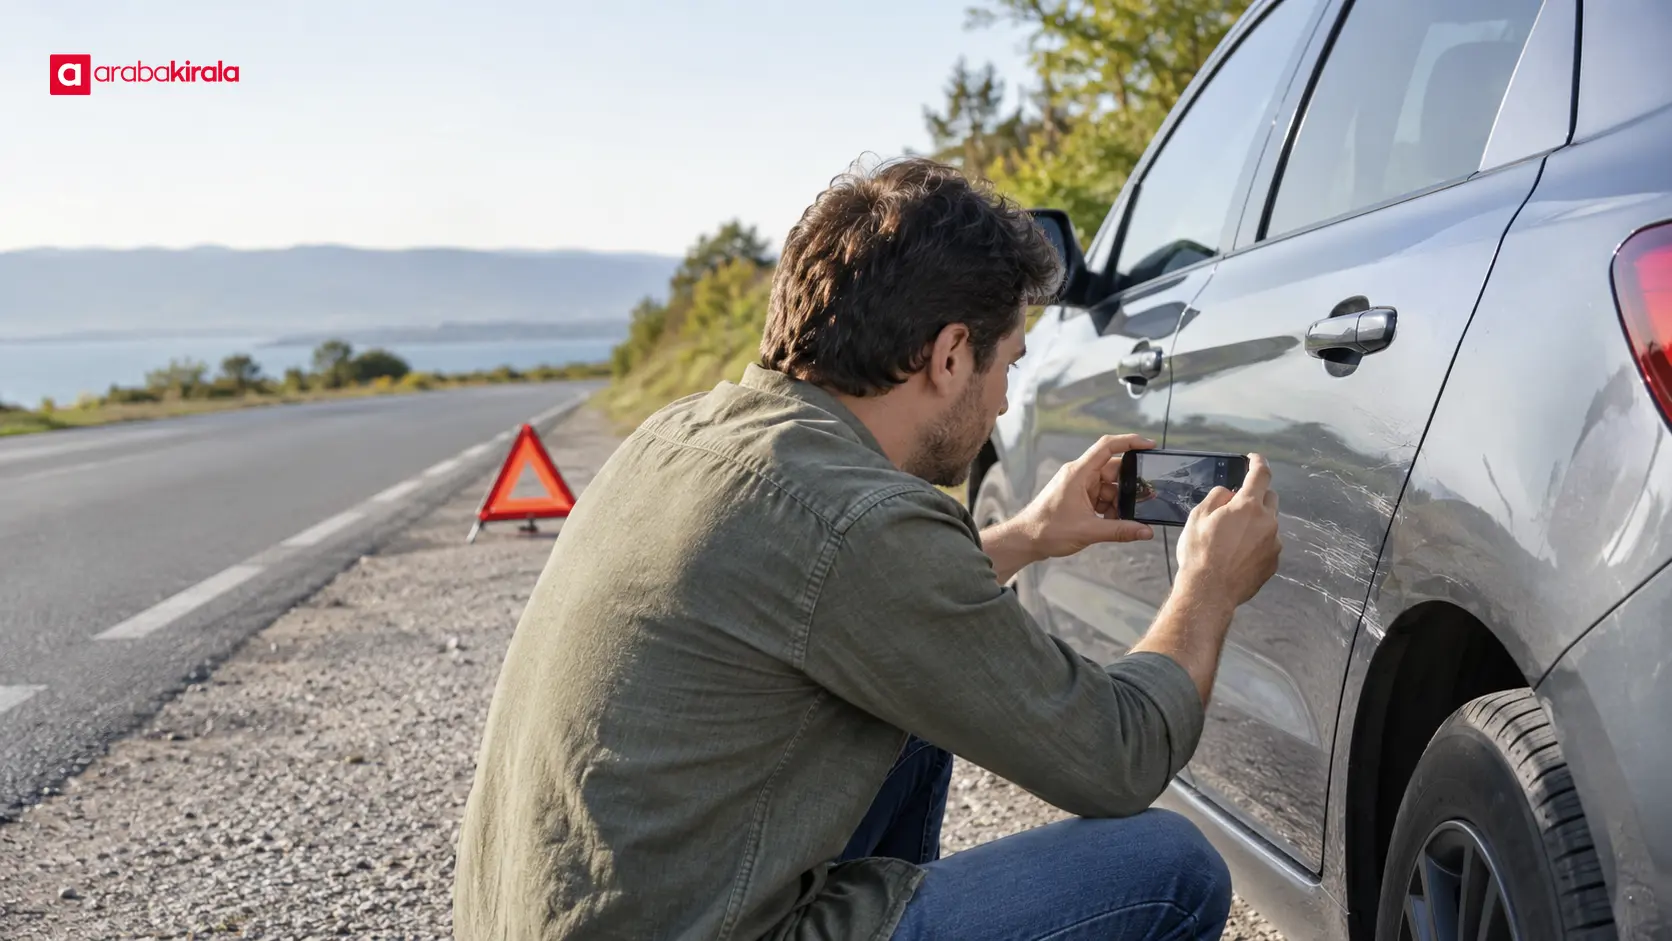
People’s safety comes first. Do not step into traffic or ignore hazards to take photographs or gather documents. In an emergency, contact the appropriate emergency service. Once it is safe, record the date, time, and location; vehicle positions; visible damage; and relevant contact details while respecting privacy.
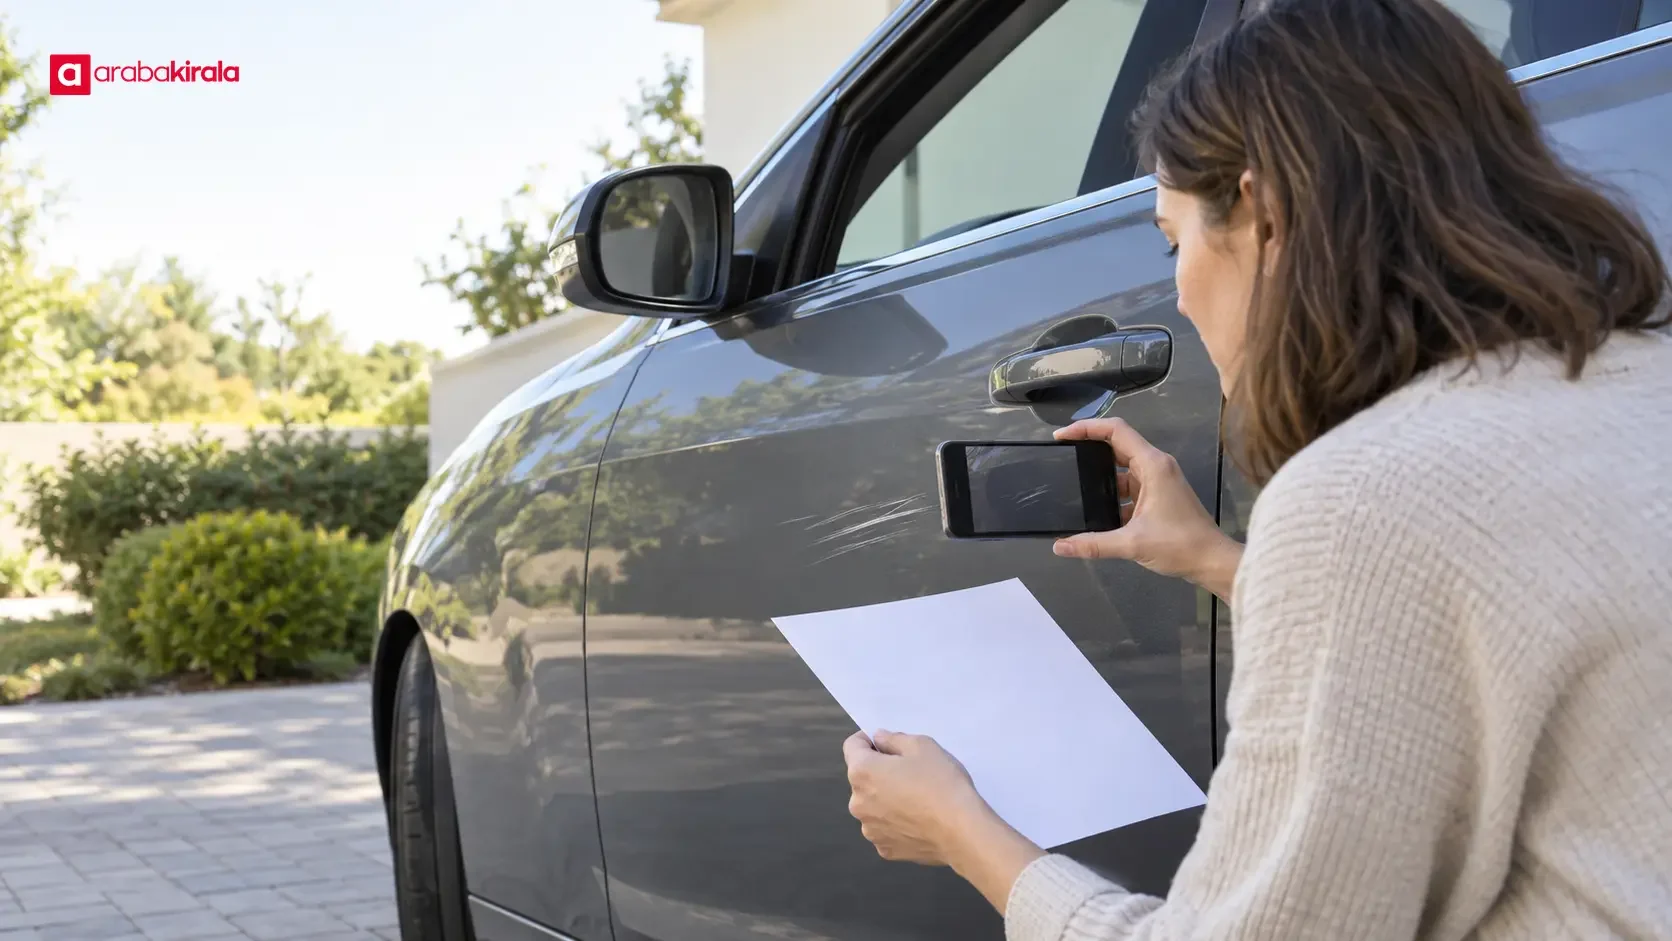
Photographs or video can help document the scene as it appeared, but they never take priority over safety. Keep original files, avoid changing their date information, and do not distribute personal details unnecessarily. If the insurer or policy calls for supporting documents, confirm exactly what is requested and how it should be sent.
A practical first-record routine
- Keep your policy number and vehicle details accessible.
- Write a concise, factual timeline of the event.
- Store photos, reports, correspondence, and other records in one folder.
- Log the date, channel, and reference number for each submission.
- Keep responses to requests for more information with the same file.
Reduce the risk of incomplete or inaccurate information
Separate what you observed from what you inferred. Do not present an uncertain time or cause of damage as definite; identify the uncertainty and ask how it can be clarified. Before sending an account, check that its dates, location, and sequence are consistent with the supporting records. If you later need to correct information, refer to the earlier notice, describe the correction in writing, and keep the updated acknowledgement.
Before attaching a document, check that it is legible, includes all relevant pages, and is the intended file. Share sensitive information only through a channel that has been requested and appears appropriate. A record of which files were received makes follow-up easier.
Notification and claim assessment are different stages
After a notice, the insurer may request more information, open a file, or explain the review process. Those steps do not establish that coverage applies or that a claim has been decided. The policy’s coverage, limits, deductibles, and exclusions are considered alongside the evidence about the event. If a response is unclear, ask whether it is simply confirmation of receipt or a decision about the claim.
If new information or documents become available while a review is underway, identify how they relate to the earlier notice. Confirm that additions have been placed on the file and ask what the next step is. Avoid assuming a fixed processing time; keep the current explanation provided for your case.
Frequently asked questions
What if I cannot find a clear notification deadline?
Review the relevant special conditions and any text they reference. If the deadline or its starting point remains unclear, ask the insurer for written clarification promptly and keep a record of the conversation. Do not invent a specific deadline to fill the gap.
Is a phone call enough?
That depends on the method stated in the policy and the needs of the event. If you provide information by phone, request a reference number and written acknowledgement where available, and ask separately whether documents must also be sent. Note the instructions you receive.
Are photographs enough to submit a damage claim?
There is no single document list for every event. Images may help show the condition, but additional records or documents may be requested. Confirm the case-specific list and submission method.
How long should I keep the records?
It is useful to keep documents and correspondence organized until the file is resolved and related follow-up needs have ended. Do not assume a particular legal retention period or data obligation; consult relevant official guidance if you need a precise answer.
Next step: make a short process note from your policy
Write down the events that require notice, the stated start of any time period, the contact method, the initial information requested, and how to obtain confirmation. If an incident occurs, prioritize safety, provide factual information through the specified channel, and retain the reference number. When policy-specific details are unclear, request a written explanation from the insurer. A little preparation makes the notification duty easier to understand and the follow-up easier to manage.
Legal Disclaimer: All content, articles and information on the Araba Kirala website are provided solely to inform users. No information shared on this website constitutes definitive advice or guidance. Araba Kirala Teknoloji A.Ş. and its authors cannot be held responsible for any direct or indirect damages arising from the application of information on the website. For all questions and requests regarding car rental, please contact the office from which you will rent your vehicle.